

In 2022, Panama will enforce two new obligations on entities: exclusively asset holding companies will be subject to the requirement to maintain accounting records going back five years, and both «commercial» entities operating outside Panama and exclusively asset holding entities will be obliged to submit annual accounting records to their Resident Agents.
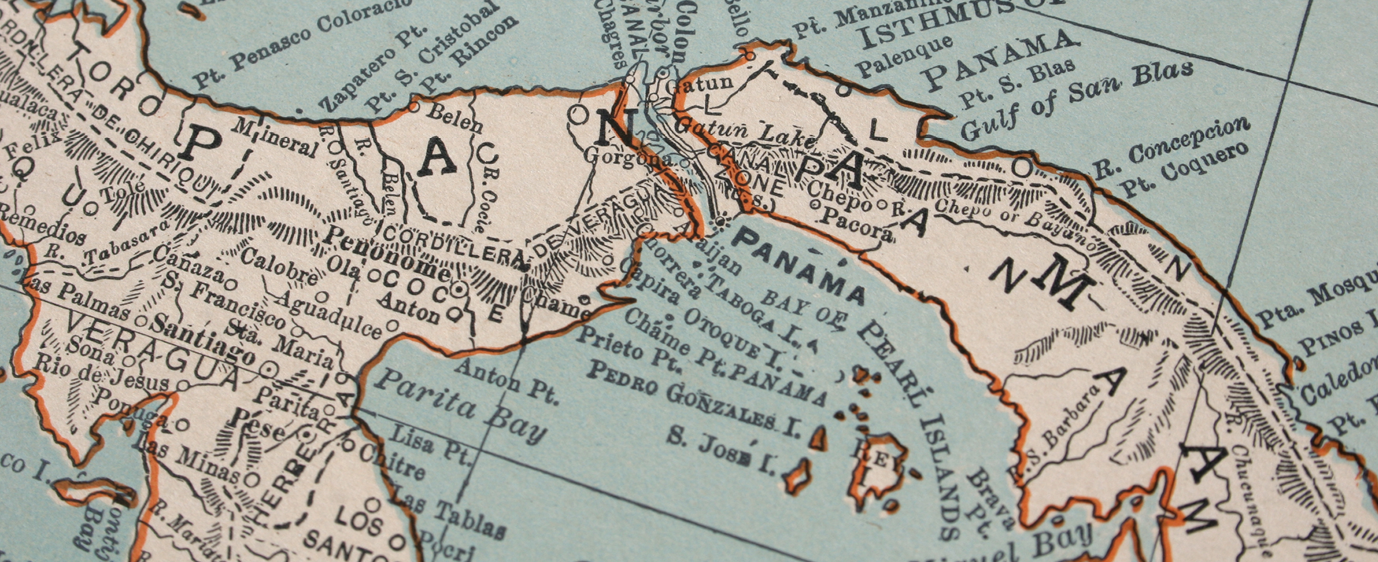
Be aware: this appears to be part of a trend that is likely to spread to other offshore jurisdictions.
Legal background (a brief summary)
Law 52 of 2016 («Law 52») (in force as of 01.01.2017) obliged Panama companies conducting business outside of Panama to maintain accounting records and supporting documents for a minimum of five years. These records had to be provided to the company’s Resident Agent upon request. If the records were not provided within a set period, the Resident Agent was obliged to resign as the company’s Resident Agent.
Further, the Public Registry would refuse to register a deed of dissolution unless the Resident Agent of the subject company provided a declaration that they held accounting records of the company going back five years.
As of 11.11.2021, Law 52 was amended by Law 254 of 2021 («Law 254»). Amongst other amendments to Law 23 and Law 129, Law 254 brought exclusively asset holding Panamanian entities within the scope of Law 52, meaning they too must comply with the requirement to maintain accounting records and supporting documents going back five years.
In addition, all entities within the scope of Law 52 are now required to submit annual accounting records to their Resident Agent.
What must be submitted?
Pure asset holding entities must provide information showing the value of the assets held, the income received from such assets and the liabilities relating to those assets.
Entities performing commercial actions outside of Panama must provide a journal and a ledger.
All entities must provide documents and information to support these accounting records if called to do so by the competent authority.
Deadlines
31.12.2021 – end of the fiscal year.
30.04.2022 – first deadline for the submission of accounting records for the preceding fiscal year to the Resident Agent.
Going forward, all entities will have to submit to their Resident Agent annual accounting records for the preceding fiscal year by 30 April.
Penalties
An entity that does not comply with Law 254 may be subject to a fine ranging from USD 5’000 to USD 1m, depending on the seriousness of the offence.
Will this affect jurisdictions other than Panama?
The legislative changes introduced by Law 52 and Law 254 were in response to pressure from the OECD to improve international tax transparency and help combat money laundering, terrorist financing and the financing of the proliferation of weapons of mass destruction.
Panama is not the only offshore jurisdiction within the OECDs scope, and it is likely that similar pressure will be applied elsewhere, meaning that other jurisdictions may well introduce similar accounting requirements.
How we can be of assistance
Leo Trust has been involved with offshore entities for over 40 years and has particular technical competence regarding Panama. We can ensure your compliance with the new requirements through the preparation of suitable accounting records and general guidance throughout the process.
Given the fast-approaching deadlines, and the threatened penalties, action should betaken without delay. Please contact your Leo Trust relationship manager as soon as possible to discuss your individual requirements.
_
This article is aimed at providing a general overview and summary of the issue. It is non-binding, and does not and should not be taken to constitute legal advice.
Discover the importance of succession planning for BVI entities and explore options to improve it in our expert article – contact us at corporate@leotrust.ch for more details and an in-person meeting.
The long-awaited updated of Leo Trust Switzerland’s Economic Substance & Beneficial Ownership Reporting general overview of various jurisdictions is available.

